Showing posts with label Bonds. Show all posts

Saturday, March 9, 2013

How Much Will Your Bond/CD be Worth in N Years? (calculator)

This Calculator Computes the Future Value of Your Bond/CD for Any Amount, Number of Years, and Interest Rate


Enter data only in the colored cells below.
Note: normal/annual compounding is once a year; semi-annual is 2 times/year; quarterly is 4 times/yr; etc. Be sure to enter interest rates as decimal amounts - 0.03 for 3%, 0.025 for 2.5%, etc.


Saturday, July 21, 2012

Interest Rate Forecast for 5-Year Treasury Notes

In this post, we forecast the yields for five-year treasury notes/bonds over the next five years using the same technique we used in an earlier post. In the earlier post, Where Are Interest Rates Headed?, we used the current yield curve to derive the yield curve as it is expected to be one, two and five years in the future. In effect, this post takes the results from that post and looks at them through a different lens.

Market Forecast of Five-Year Interest Rates for Next 5 Years


Interest rate forecast for 5-year U.S. Treasury Notes/ Bonds
Market Forecast of Five-Year Interest Rates

In the graph above (click to expand) the solid blue line represents five-year U.S. Treasury Notes. Year zero shows the "current" yield of 0.68% (To be consistent with the graph in the previous post, "current" is as of June 15, 2012). The remaining points show the expected yield on five-year treasuries from one to five years in the future. The expected yields were derived from

Friday, June 22, 2012

Where Are Interest Rates Headed?

This post describes a methodology for using the current yield curve to forecast future interest rates.

In the current economic environment, the direction of interest rates is a critical issue for many investors -- especially for retirees. You probably know that you can use the yield curve to forecast the direction of the economy. But, did you know that you can also use the current yield curve to forecast the shape of the yield curve one, two or three years or more in the future? Read on.

The Bond Market's Forecast of Interest Rates 1, 2 & 5 Years From Now

Future interest rate forecast: Yield curve 5 years from now
Market Forecast of Future Yield Curve/ Interest Rates


In the graph above (click to expand), the heavy black line is the current yield curve (as of June 15, 2012). The other three lines are the yield curves as they are expected to be 1, 2 and 5 years in the future. The shape of the future yield curves was derived directly from the current yield curve.  As you can see from the chart, the forecast is for rates to remain depressed, even as they rise gradually over the next five years. Two years from now (the green line), the one-year rate is forecast to be barely above 0.5%; five years from now (the dotted red line), the five-year rate is forecast to still be less than 3%.

Deriving Future Yield Curves From the Current Yield Curve

To understand how this model/spreadsheet works, consider the following. If we know the current one year interest rate and the current two year interest rate, we can calculate

Wednesday, February 22, 2012

Why Mutual Fund Owners Earn Lower Returns Than The Funds They Own(!)

Mutual fund owners earn lower returns than their funds report. And, it's not because the funds are lying.

In an earlier post we saw that investors earn significantly less than the theoretical, published overall market returns. In this post we'll see that they also earn less than the published returns for the funds that they actually own! How can that be? Read on.

Mutual Fund Returns vs. Investor Returns (aka Dollar-Weighted Returns)


investor returns, asset-weighted and dollar-weighted returns

The graph above (click to expand) shows that between 1991 and 2010 the return for the average stock fund was 9.9% per year. For this same period, the average stock fund investor earned just

Saturday, October 8, 2011

Real World Expenses Reduce Published Market Returns

The stock market returns published in this blog, and in most other publications, are theoretical returns. In the real world, investors incur expenses that reduce the reported market returns. This post overviews those expenses and shows how they can easily reduce a retirement portfolio to less than 50% of its theoretical value!

Graph shows costs reduce ROI of stock investments

Market or Index Returns

Elsewhere on this site, we have seen that over long periods of time, the DJIA (Dow Jones Industrial Average) has returned about 10% per year. For example, the return from year-end 1990 to year-end 2010 was 10.2%. That was the return earned by the market, as represented by the Dow index, reinvesting all dividends, and ignoring all expenses -- including taxes. Unfortunately, partly because of expenses, those returns do not accurately reflect

Monday, July 11, 2011

What Will My Bond or CD be Worth in 5 Years?

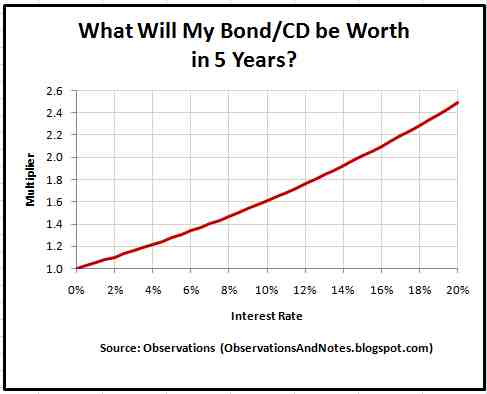
Here's an easy way to approximate what $5,000, $20,000, $50,000, or any other amount will grow to in 5 years. It works for bonds, CDs -- any investment that you expect to compound at a fixed annual rate. You can also use this graph to ballpark the results for multiples of 5 years -- e.g., 10, 15, 20 or 25 years.

NEW! Try my new interactive bond interest calculator. It does the same calculations as the graph below, but for any number of years, and for any interest rate. Then come back to this post; graphs are still better for seeing the big picture.

Because stock market results are not consistent, for stock market results see  the variability of 5-year stock market returns instead.

Approximates Results from the Calculator/Spreadsheet

The interactive bond calculator will give you precise results.  However, since the calculator may not work in some browsers, I'm providing this graph as a way to approximate the results.

What Will my Bond or CD be Worth in 5 Years?


5-year compound growth/ interest rate calculator/estimator for $5,000 $10,000 $15,000

The graph above (click to expand) shows how rapidly a bond or CD of any denomination will grow in five years. Given an interest rate, indicated on the horizontal axis, the "multiplier" on the vertical axis tells you what your investment will be worth in 5 years (assuming earnings reinvested each year, and no taxes). The multiplier is the same regardless of how much money you invest. For example,

Wednesday, April 27, 2011

What Will $10,000 be Worth in 10 Years? (CDs, Bonds, Dollars...)

Here's an easy way to approximate what $10,000, or $100,000, or any other amount will be worth in 10 years. It works for bonds, CDs -- any investment that you expect to compound at a constant annual rate. You can even use it to ballpark the results for 20, 30, 40 or 50 years. (Note: to estimate returns for 5 years, and multiples of 5 years, see What Will my Bond or CD be Worth in 5 Years?.) In all cases, you supply the interest rate, and read the multiplier off the chart.

NEW! Try my new interactive bond interest calculator. It does the same calculations as the graph below, but for any number of years, and for any interest rate. Then come back to this post; graphs are still better for seeing the big picture.

For the future value a dollar, see What Will $100 be Worth in 10 - 20 Years? Finally, because stock market results are not consistent, for stock market results see What Will a $10,000 Stock Market Investment be Worth in 10 Years? instead.

Approximates Results From the Calculator

The interactive bond calculator will give you more accurate results. However, since the calculator may not work for all browsers, I'm providing this graph as a way to approximate the results.

What Will a $10,000 Bond/CD be Worth in 10 Years?


10 year compound growth/ interest rate calculator/estimator
Note: the multipliers (on the vertical axis) range from 1 to 10. The bottom (labelled) line corresponds to a multiplier of 1, the next (unlabelled) line to a multiplier of 2, etc. The lines are not the same distance apart because the vertical axis uses a log rather than linear scale (see about log graphs).

What Will a $10,000 Bond/CD be Worth in 10 Years at 10%?

In the graph above (click to expand), find 10% on the horizontal axis. The multiplier looks to be about 2 2/3 (it's actually 2.6). So, $10,000 at 10% for 10 years is approximately ($10,000 x 2.6=) $26,000.  The multiplier is the same regardless of how much money is invested. This same multiplier works for $1,000, $100,000, or $364.27.

Thursday, April 21, 2011

The Decrease in Purchasing Power of the U.S. Dollar Since 1900

(Last updated November, 2020)
The declining value of the dollar is one of the biggest threats to retirees, and near retirees. This post explores the history of that decline over the past 100 years or so, with graphs going back to 1900.

One of the biggest threats to my own retirement plan is the cumulative impact that future inflation rates will have. Readers whose retirement income is not cost-of-living-adjusted need to evaluate the impact that inflation and the declining value of the dollar will have on their income, and be prepared to supplement their income as necessary.

Try my interactive inflation calculator that will convert any prior year dollars to any later year  right on your screen.  Then come back to this post and look at the bigger picture.

Decreasing Purchasing Power of the U.S. Dollar: What's $10,000 in 1900 Worth Today?


100 years of inflation history: declining value of the dollar. to 2020

The graph above (click to expand) shows that if a shopper were magically transported from the year 1900 to 2020, the $100 bill that he had in his wallet in 1900 would now be worth only $3.06! That is, $100 in 2020 would have the purchasing power that $3.06 had in 1900; $10,000 would be worth only $306 today. That's a 96.9% decrease in buying power. Our shopper would consider current dollars virtually worthless. (Note: the calculations in the post were made using my inflation calculator.)

The Cumulative Impact of Inflation on Retirement Planning

Since 1900, U.S inflation has averaged about 3.0% per year. However, even at that moderate rate, the cumulative effect is

Tuesday, March 15, 2011

100 Years of Inflation Rate History

Inflation can be devastating; while it has been under control for the past 25 years, there is no guarantee that it will remain so. Since this blog emphasizes long-term planning, it is important that we address the issue of inflation, and the impact that the declining purchasing power of the dollar has on our investments. For perspective, as always, let's first look at the past century.

U.S. Inflation Rates since 1900

Yearly change in consumer price index (CPI-U) 1900-2012
U.S. Yearly Inflation since 1900

The above chart shows the yearly rate of inflation as measured by the Consumer Price Index for All Urban Consumers (CPI-U) for the past 100 years. By early 2012, prices were more than 28 times higher than in 1900 -- the CPI increased from 7.9 to 226.7. Phrased differently, a dollar buys 28 times less now than a dollar bought in 1900 (see inflation calculator). While inflation has averaged only 3% for the complete period, and also 3% since 1982, such subdued inflation has clearly not always been the case. The graph shows several periods where inflation rose to 10% or more. Here's a quick summary of inflation's impact on some key areas.

The Impact of Inflation: A Dollar Buys a Lot Less Than it Used To

Inflation increases the

Sunday, December 12, 2010

U.S. 10-Year Treasury Note Real Return History

This post graphs the history of "real" (i.e., inflation-adjusted) returns for investors in U.S. Treasury 10-Year Notes beginning in 1900.

100 Years of Treasury Note Interest Rate History documents U.S. interest rates over the past century based upon the rates in effect at the "time of issue" -- the "coupon rate." For buy and hold bond investors, that was also the investor's nominal rate of return.  However, because of inflation, the investor's real return is almost always less than the coupon rate. For short maturities, the investor's return is very close to that coupon rate -- again, assuming he holds to maturity. However, over a 10-year period, inflation can have a significant impact. In this post, we'll evaluate that impact.

10-Year Treasury Note Real Returns: The Impact of Inflation

graph of 10-year T-Bond inflation-adjusted returns (to 2012)
10-Year Treasury Note Real Returns

The above graph uses Robert Shiller's Irrational Exuberance data to approximate the historical "real" returns of investors in 10-year Treasury Notes from 1900 to 2002 (see

Tuesday, November 30, 2010

Analyzing Treasury Bond Interest Rate History since 1900

The chart below of bond interest rate history has negative implications not just for some bonds, but potentially for stocks & housing as well. This post complements 100 Years of Treasury Note Interest Rate History, the previous post which graphed the month-by-month rates.

Together, the two posts make it clear that we are currently experiencing historically low yields. That suggests a future of rising interest rates. Rising rates have negative implications not only for many bond investors, but potentially for the stock market and housing market as well.

Treasury Bond Interest Rate History: Yearly Frequency Histogram


frequency histogram of 10-year Treasury Note interest rates (yields) for 100 years


The above histogram/frequency distribution of treasury yields is based on the same data as the chart in the previous post (click on image to expand). From 1953 onward, the source data is

Wednesday, November 17, 2010

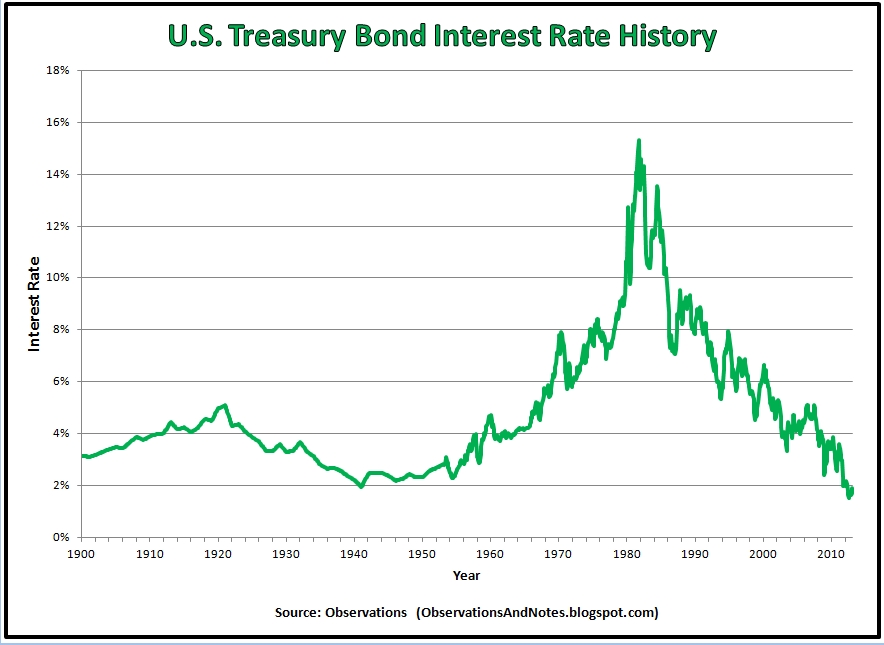
100 Years of Treasury Bond Interest Rate History

Investors expecting bond funds to perform as well in the next 10 years as they have in the last 10 will be disappointed. Bonds can play an important role in investor portfolios, reducing volatility and increasing the predictability of returns. However, the stellar performance of bond funds -- especially longer-term funds -- as yields have declined over the last 30 years will not be repeated anytime soon. Not only that, there is even the risk of negative returns.

U.S Treasury Bond Interest Rate History Since 1900


100-year history of 10-year Treasury Note interest rates (yields) 1900 - 2013
U.S. Treasury Bond Interest Rate History

The graph above (click on image to expand) shows U.S. interest rates beginning in 1900. From 1953 onward, the rates are

Monday, October 4, 2010

The Importance of Bond Duration

Duration is a way to measure interest rate risk; it is a more precise measure than maturity alone.

The Impact of Duration on Sensitivity to Rate Changes


The graph above demonstrates the impact that duration has on the sensitivity of bond prices to interest rate changes. This post explains how duration is calculated and

Thursday, September 23, 2010

Yield to Maturity (YTM) & Interest Rate Risk

This post introduces YTM, and explains why rising interest rates result in falling bond prices.


Bond Price and YTM/Interest Rates

The above graph summarizes the relationship between the two; the post helps explain why this is so.


Calculating a Bond's Yield to Maturity
In the fundamentals of investment valuation post, we introduced the concept of present value, and arrived at

Tuesday, August 24, 2010

Fundamentals of Investment Valuation

As we saw in Bond Basics, a bond typically represents an obligation by the borrower to pay fixed amounts of interest on fixed dates, and to repay the principal amount when the bond matures. The relative certainty of the amounts and dates is the major advantage of bonds compared to other possible investments. Bond valuation, then, is assigning a value or price to this stream of payments.

Intro to Present Value: What is $105 a Year from Now Worth to You Now?

The key to pricing bonds is the concept of Present Value, or PV. Suppose you can earn 5% interest and you have $100. From the bond basics post we know that interest = principal x rate x time. So, in one year $100 will earn ($100 x 5% x 1 =) $5 in interest.

Therefore, a year from now you can have $105 -- your original $100, plus $5 in interest. It is in that sense that the "present value" of $105 a year from now is said to be $100; $105 a year from now is worth $100 today. Note that the

Monday, July 26, 2010

Bond Basics

What Is a Bond?

A bond is a loan. When you buy a bond, you are lending money to the bond's issuer. Generally, the loan is for a fixed amount of money, the principal -- or face amount -- for a fixed length of time. At the end of that time, the bond is mature; the borrower pays off the loan by paying off the face amount. Most often, the loan is at a fixed rate of interest, the interest being due on a fixed schedule during the life of the loan (e.g., quarterly or yearly).

Technically, not all fixed income instruments are bonds. However, in this post I am using the term bond loosely to include not just bonds, but other fixed income instruments such as bills, notes and certificates of deposit as well.

Basic Bond Math: Calculating Interest

Saturday, January 30, 2010

Investing: Subject Index

TABLE OF CONTENTS


INVESTING-GENERAL, BONDS & INFLATION


Inflation

The Declining Value of a Dollar: 100 Year History: Shows the dramatic decrease in purchasing power over time.
Inflation Calculator: Calculates inflation rate between any two years. Converts current dollars to/from prior years.
What Would $10,000 in 19xx be Equivalent to Today? graph to convert dollar amounts from any prior year to their approximate equivalent today.
How Much Will $100 be Worth in 10-20 Years? converts today's dollars to equivalent in future years.
100 Years of Inflation History: graph, + summary of impact of inflation on bonds, stocks, housing....
Inflation Calculator/Spreadsheet: calculates inflation rate and change in purchasing power between any two years -- e.g., between 1970 & 1980.